
Mortgage Rates Hit 7.40%: What Kitsap and Olympic Peninsula Buyers Need to Recalculate
If you ran your home-buying numbers last month—or even last week—it is time to look at them again.
Freddie Mac reported that the average 30-year fixed mortgage reached 7.40% on October 8, 2026. That was up from 7.28% one week earlier and 6.30% one year earlier. The average 15-year fixed mortgage reached 6.73%.
The simple version: the same loan now comes with a higher estimated monthly payment. The house did not get an extra bedroom overnight. The financing just became more expensive.
That does not automatically mean you should stop looking in Kitsap, Jefferson or Clallam County. It means your search should start with a payment you can comfortably carry—not with the highest price a calculator says you might qualify for.
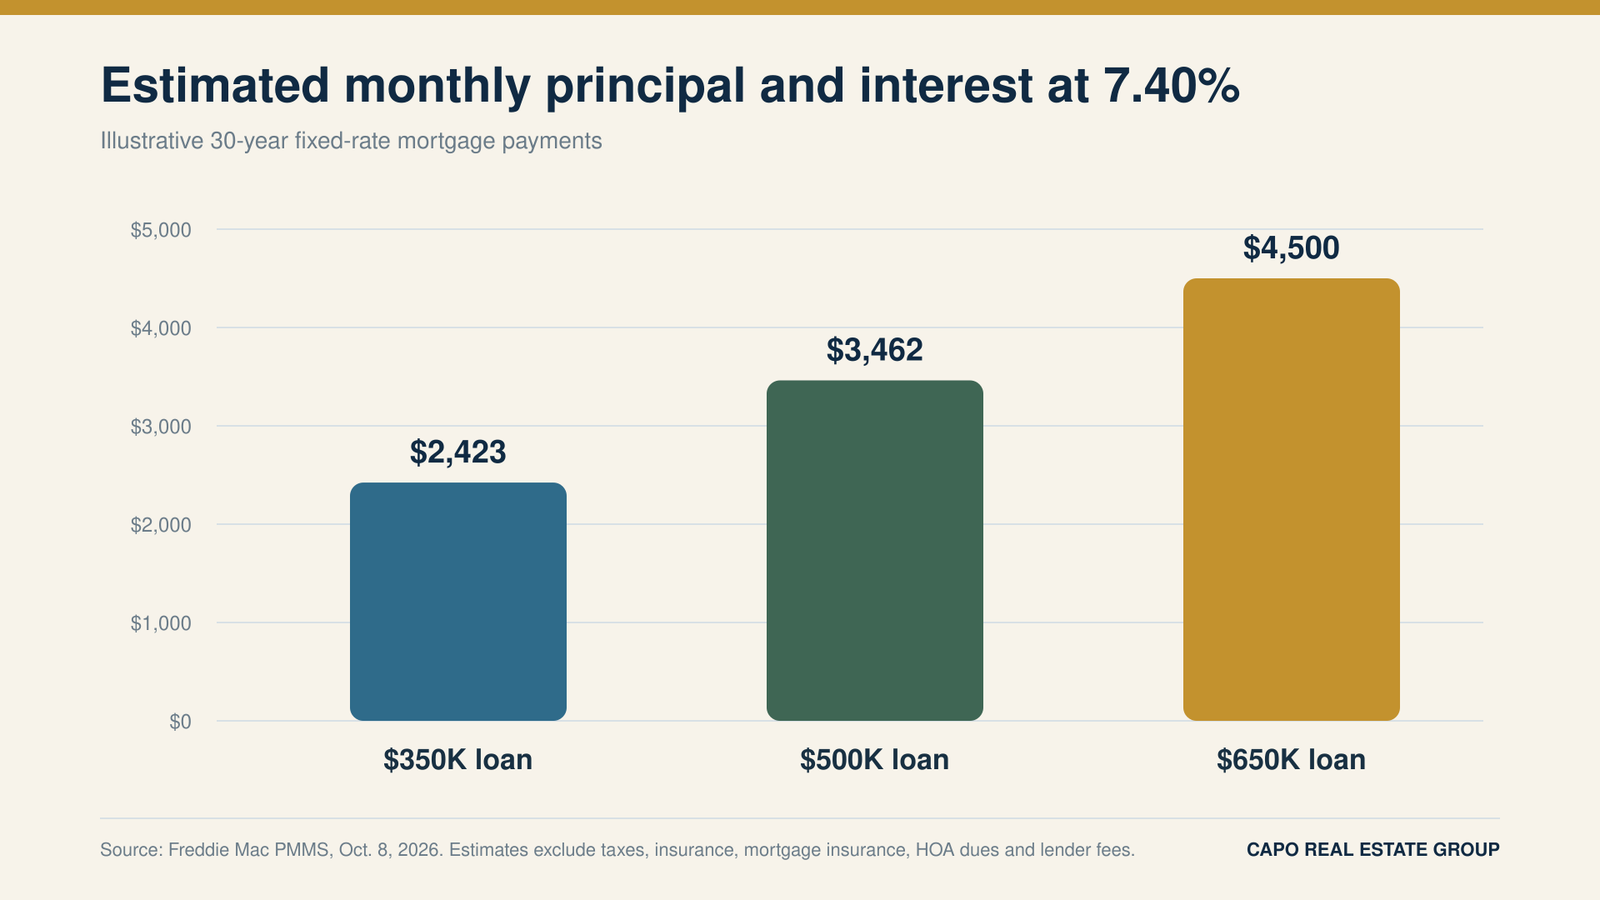
Quick answer: At 7.40%, the estimated principal-and-interest payment is about $2,423 on a $350,000 loan, $3,462 on a $500,000 loan and $4,500 on a $650,000 loan. These examples do not include property taxes, homeowners insurance, mortgage insurance, HOA dues or lender fees.
What does a 7.40% mortgage rate mean in dollars?
Interest rates sound abstract until they show up in a monthly payment. Here are three examples using a 30-year fixed-rate loan.
| Loan amount | Estimated monthly principal and interest |
|---|---|
| $350,000 | $2,423 |
| $500,000 | $3,462 |
| $650,000 | $4,500 |
These are loan amounts, not purchase prices. If you buy a $600,000 home with a $100,000 down payment, for example, the starting loan amount would be approximately $500,000 before considering financed fees or other adjustments.
Your full housing payment may also include:
- Property taxes
- Homeowners insurance
- Mortgage insurance, when applicable
- HOA or condominium dues
- Flood insurance, when required
- Other property-specific costs
That is why a listing-price search alone can be misleading. Two homes at the same price can produce very different total monthly costs.
The one-week change is not the biggest story
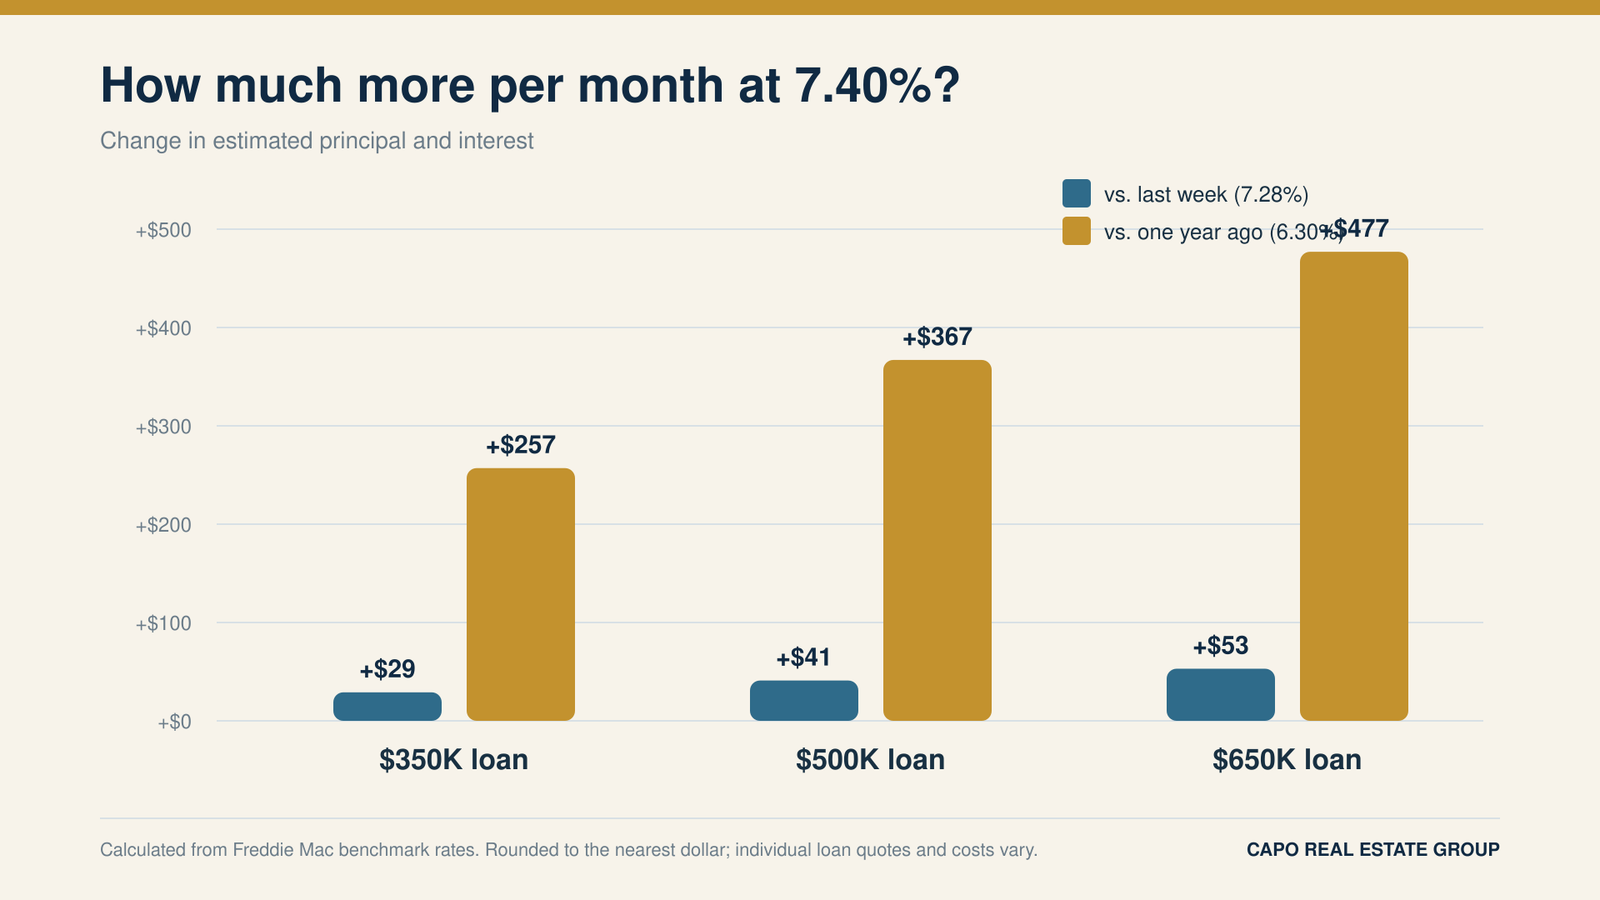
Moving from 7.28% to 7.40% adds roughly $29 to $53 per month in these examples. That matters, but the comparison with one year ago is much larger.
| Loan amount | Increase from 7.28% | Increase from 6.30% |
|---|---|---|
| $350,000 | $29/month | $257/month |
| $500,000 | $41/month | $367/month |
| $650,000 | $53/month | $477/month |
On a $500,000 loan, the estimated principal-and-interest payment is about $367 more per month than it would be at last year’s 6.30% benchmark. Over twelve months, that is roughly $4,400 in additional payments—before taxes, insurance and other costs.
That year-over-year difference is the number most likely to affect a buyer’s comfort level or loan qualification.
Is 7.40% the rate you will personally receive?
Not necessarily.
Freddie Mac’s Primary Mortgage Market Survey is a national weekly average based on thousands of mortgage applications submitted through its Loan Product Advisor system. Its published borrower profile generally reflects conventional, conforming, owner-occupied, single-family purchase loans with good or excellent credit and about 20% down.
Your actual quote may be higher or lower depending on factors such as:
- Credit profile
- Down payment
- Loan type
- Loan amount
- Property type and occupancy
- Discount points or lender credits
- The date and length of your rate lock
The Freddie Mac benchmark also is not the same thing as an APR, and its current survey does not report average lender fees or points. Use it as a market temperature check—not as a promise of the rate waiting for you.
What should Kitsap and Olympic Peninsula buyers do now?
1. Ask for an updated payment—not just an updated rate
If your preapproval or payment estimate is several weeks old, contact your lender before falling in love with a home. Ask for the estimated total monthly payment, including taxes, insurance, mortgage insurance and HOA dues when applicable.
An updated rate without the full payment is only half an answer.
2. Give your real-estate broker a monthly ceiling
Tell Capo Real Estate Group the maximum monthly housing payment you want to stay under. That can produce a more useful search than simply entering the highest purchase price on your approval letter.
For example, a buyer might be comfortable financing one price in Bremerton but need a different ceiling for a Bainbridge Island condominium with HOA dues or a rural Clallam County property requiring additional insurance or maintenance planning.
3. Compare written loan offers
The Consumer Financial Protection Bureau recommends requesting and comparing Loan Estimates from multiple lenders once you have a specific property and accepted offer. Compare the interest rate, APR, estimated cash to close, lender charges and whether the quote includes points—not merely the advertised rate.
A lower rate is not automatically the least expensive loan if it requires substantial upfront costs.
4. Ask about seller contributions—but let the lender do the math
Some transactions may allow the seller to contribute toward permitted buyer closing costs or a temporary or permanent rate reduction. The amount and usefulness depend on the loan program, contract, appraisal, buyer qualification and lender rules.
Do not assume a seller-paid rate reduction is always better than a price reduction. Ask the lender to prepare comparable scenarios so you can see the monthly payment, cash required and break-even period.
5. Leave room for the house to be a house
A mortgage is not the only expense that arrives after closing. Homes need repairs. Appliances develop personalities. Waterfront, acreage and older properties can have additional maintenance, insurance or utility considerations.
Being approved for a payment and being comfortable with it are not the same thing.
Should you wait for mortgage rates to fall?
No one can promise when rates will fall, how far they will fall or what home prices and competition will be doing at that time.
A better question: Can I find a suitable home with a total payment I can comfortably manage under today’s verified numbers?
If the answer is no, waiting may be sensible. If the answer is yes, you can evaluate the property and financing without betting your entire decision on a future rate forecast.
Buying now also does not guarantee that refinancing later will make sense. Refinancing depends on future rates, qualification, property value, loan balance and closing costs.
What this means in Kitsap, Jefferson and Clallam counties
The interest-rate change affects all three counties, but the search strategy may differ. The following context comes from the Northwest Multiple Listing Service September 2026 Market Snapshot, released October 6:
- Kitsap County: Inventory remains comparatively tight, so buyers should watch older listings and price reductions instead of assuming every seller will negotiate.
- Jefferson County: More listings and completed sales do not guarantee lower prices. Compare payment, property condition and location rather than relying on a countywide headline.
- Clallam County: A lower countywide median can create more options for payment-sensitive buyers, but rural utilities, wells, septic systems and insurance can materially affect the full cost of ownership.
The practical move is to combine current financing numbers with a property-specific search.
Frequently asked questions
What is the monthly payment on a $500,000 mortgage at 7.40%?
The estimated principal-and-interest payment is approximately $3,462 per month for a 30-year fixed-rate loan. Property taxes, insurance, mortgage insurance, HOA dues and lender fees are not included.
How much did mortgage payments change this week?
The Freddie Mac benchmark increased from 7.28% to 7.40%. That raises the estimated principal-and-interest payment by approximately $29 per month on a $350,000 loan, $41 on a $500,000 loan and $53 on a $650,000 loan.
Does a 7.40% national average mean my lender must offer that rate?
No. It is a national benchmark, not an individual quote. Your credit, down payment, loan program, property, points, lender fees and lock date can change the rate and total cost.
Should I update my mortgage preapproval?
If your preapproval or payment estimate is several weeks old, ask your lender whether the payment and maximum loan amount still work under current rates. Do this before making an offer.
Can a seller pay to reduce my mortgage rate?
Seller contributions may be allowed under certain loan and contract rules. Ask your lender to confirm the permitted amount and compare the benefit with a price reduction or other use of the credit.
Get a payment-first home list
Capo Real Estate Group helps buyers across Kitsap, Jefferson and Clallam counties search according to the numbers that matter in real life—not merely the largest price on a preapproval letter.
Tell us your preferred community, comfortable monthly housing-payment ceiling, estimated down payment and any commute, property-type or lifestyle requirements.
Mike Capobianco is a real estate broker with LPT Realty LLC.
Sources and calculation notes
- Freddie Mac Primary Mortgage Market Survey, October 8, 2026
- Consumer Financial Protection Bureau: Choosing a Loan Offer
- Northwest Multiple Listing Service: September 2026 Market Snapshot
Payment illustrations use the standard fixed-rate amortization formula for a 30-year loan with 360 monthly payments. Figures are rounded to the nearest dollar. They exclude property taxes, homeowners insurance, mortgage insurance, HOA dues, discount points, lender charges and other closing costs. This article provides general educational information and is not a mortgage approval, rate quote, tax advice or legal advice.
CapoRealEstateGroup.com
